ORD 1859/2023-9 · CONCURSO 36/2012 · ARRECIFE · RICPE · NPL / CREDIT-RIGHTS 360
This is not only an arithmetic dispute.
The controlling question is how an original banking relationship comprising several economically connected instruments later diverged into two institutional lanes: the mortgage-credit assets followed the Bankia → SAREB → PH122 → CAM holder chain, while financial-product claims, originator conduct and any retained banking-side obligations remained within a separate bank/successor lane. The exact Bankia→SAREB allocation remains a primary-document question.
Important correction: the claimant is not alleging that Construcciones Acosta Matos, S.A. became an unlicensed bank merely by purchasing the loans or that it originated new regulated lending. The question is whether it acquired and exercised the asset-side creditor position after economically linked elements of the original regulated-bank package had been separated, and whether that asymmetry affected rights, obligations, remedies and later representations about Sun Park.
Status: claimant-side analysis for verification and pre-trial dialogue. It is not a finding of fraud, criminal liability, regulatory breach or professional misconduct.
Root-cause X-ray: six layers that must be reconciled
Useful evidential pressure makes every logical jump visible and identifies the source capable of confirming, narrowing or refuting it.
Connected evidence and context routes
CONTROLLED RECONSTRUCTION · 2008 ORIGIN → DISTINCT SUCCESSIONS
Two chains. One banking origin. One reconciliation still required.
Corporate/product succession must not be confused with credit-asset succession. The present evidence establishes different later lanes; it does not yet establish one single “split transaction” with all of its terms.
Controlled originating banking package17 Jun 2008 · €8.6m mortgage7 Jul 2008–7 Jan 2012 · €5m notional swap27 May 2010 · €850k second mortgage + €405k pledge
La Caja de Canarias → BFA / Bankia → CaixaBank
This lane concerns origination, the financial product, banking administration and whatever obligations or liabilities legally remained in or succeeded within the banking perimeter. CaixaBank is Bankia's universal successor and the current defendant; it was not the original lender.
Bankia → SAREB (2013) → PH122 / Meridian (2014) → CAM (20 Oct 2017)
This lane follows the credit/security position. The 2013 year and 2014 perimeter are controlled, but their native transfer instruments and schedules remain open. The 20 October 2017 PH122→CAM assignment has an exact verified date.
Native transfer instrument, LPB asset schedule, treatment of linked products/defences and allocation of retained obligations remain missing.
LSAP, asset schedule, LPB allocated price, warranties/disclosures and servicing remain missing. Open the IREA/Colliers records-custody route →
The assignment is identified in primary material. Complete Protocol 2,248, schedules, price/payment, due diligence, warranties and loan-by-loan balance remain open.
DOWNSTREAM · DISTINCT REGIMES
Credit → asset availability → investment → public support
RIC ≠ RICPE ≠ Regional Incentives ≠ ERDF. Coexistence does not prove double funding, fraud or shared knowledge. The traceability question is what propositions about title, availability, charges, assets, works, costs, employment and third-party rights were verified — or corrected — at each decision gate. See the same hotel's multiple financial lives →
Control rule: the swap contract ended on 7 January 2012, before the Bankia→SAREB transfer presently carried at year-level as 2013. The public record should therefore not say as fact that Bankia “split” a live loan+swap contract in 2013. The transfer instrument and asset schedule are required to determine which rights, defences, accounting effects and obligations remained in each lane.
Eight proof questions that must not be collapsed into one number
What was the original regulated-bank bargain?
The claimant's filed position is that the 2008 financing was structured as one economic package combining mortgage lending with a financial-risk coverage contract functionally linked to that lending. The first task is therefore to reconstruct the complete originating instruments, not to treat the later mortgage balance as if it had always existed in isolation.
When did the banking relationship diverge into different successor and holder lanes?
The controlled record shows the mortgage-credit assets later moving through Bankia → SAREB → PH122 → CAM, while the swap/financial-product lane is presently carried only through the originator/Bankia side. The swap’s contractual period ended on 7 January 2012, before the 2013 Bankia→SAREB transfer presently carried in the repository. The open issue is therefore not a proved single “split transaction”, but the exact allocation of rights, defences, accounting effects and retained obligations across the later transfer.
Who became holder of what was already recognised?
The controlled Concurso record states that the 8 February 2018 order substituted Construcciones Acosta Matos, S.A. for Promontoria Holding 122 B.V. at the then-recognised secured-credit figures: €857,373.81 and €8,194,877.88, plus contingent secured costs without an autonomous amount. Holder succession is not, by itself, an enlargement of quantum or remedies.
What exactly passed under the assignment?
The complete deed, schedules, consideration, payment mechanics, costs, notices and operative annexes remain provenance questions. Spanish Civil Code article 1528 provides that assignment of a credit includes accessory rights such as mortgage and privilege; that does not answer what the underlying credit legally comprised, what defences remained available or how a separately retained linked product affected the overall relationship.
How was the acquired creditor position used in both Concurso and Arrecife?
The credit position operated inside Concurso 36/2012 and also appears in the Arrecife mortgage-enforcement chain through procedural succession. The exact S.A./S.L. identity and title used in Arrecife require documentary reconciliation. The claimant alleges possible fraude concursal and/or fraude procesal; those characterisations require proof of each act, actor, knowledge, deception and procedural effect.
Non-bank purchaser is not the same thing as an unlicensed bank.
A non-bank purchaser can in principle acquire a credit. The present issue is narrower: CAM entered a creditor/security position created within regulated banking after the mortgage-credit asset had moved into a distinct downstream holder chain. The question is what rights, limitations, borrower protections, defences and linked economic obligations survived that succession—not whether CAM needed a banking licence merely to own the credit.
The same asset later entered a CNMV-registered RIC investment environment.
RIC Private Equity was a registered venture-capital company. Its June 2020 investor material listed Sun Park with Construcciones Acosta Matos, S.A. as the project company, subject to an “under study” caveat. In the November 2020 webinar José Acosta, speaking as CAM director general and RICPE director, described Sun Park as a portfolio project, a planned €12m four-star conversion and part of the projects offered for investors to materialise RIC. RICPE's September 2023 prospectus later identifies MYND Yaiza as “originally Sun Park” and records two financed components in portfolio, confirming downstream financing continuity without resolving the earlier title/availability questions.
Arithmetic ≠ enforceability ≠ asset availability.
Every amount and every project proposition must answer different questions: calculated how; owed under what instrument; held by whom; enforceable by what remedy; and what did that creditor position actually say about ownership or availability of the underlying hotel asset?
The credit → asset → investment nexus
Loan + linked financial-risk cover
The originating relationship arose inside regulated banking. Later holder/successor records show the mortgage-credit assets and bank/product questions following distinct institutional lanes; the exact legal allocation at Bankia→SAREB remains to be proved from the transfer instrument.
Concurso + Arrecife
CAM acquired the mortgage-credit position and accessory rights from the PH122 chain and used or relied on that creditor position in the insolvency/enforcement environment. That did not automatically confer ownership of every Sun Park unit, common area, operating right or hotel-wide economic interest.
Sun Park presented to tax-incentive investors
By 2020 the CAM/RICPE perimeter was presenting Sun Park as a project for RIC-linked investment. The webinar went beyond a neutral “under study” listing: it described portfolio inclusion, a works/financing timetable and represented CAM's three complexes as acquired with own funds and free of mortgage charges. By the 2023 prospectus the same project, renamed MYND Yaiza, appears with financed reform and job-creation components. Each stage must be reconciled with the actual title, charges, Concurso restrictions, Arrecife execution and third-party rights existing at the relevant dates.
Two Spanish visual indices already used in institutional notices
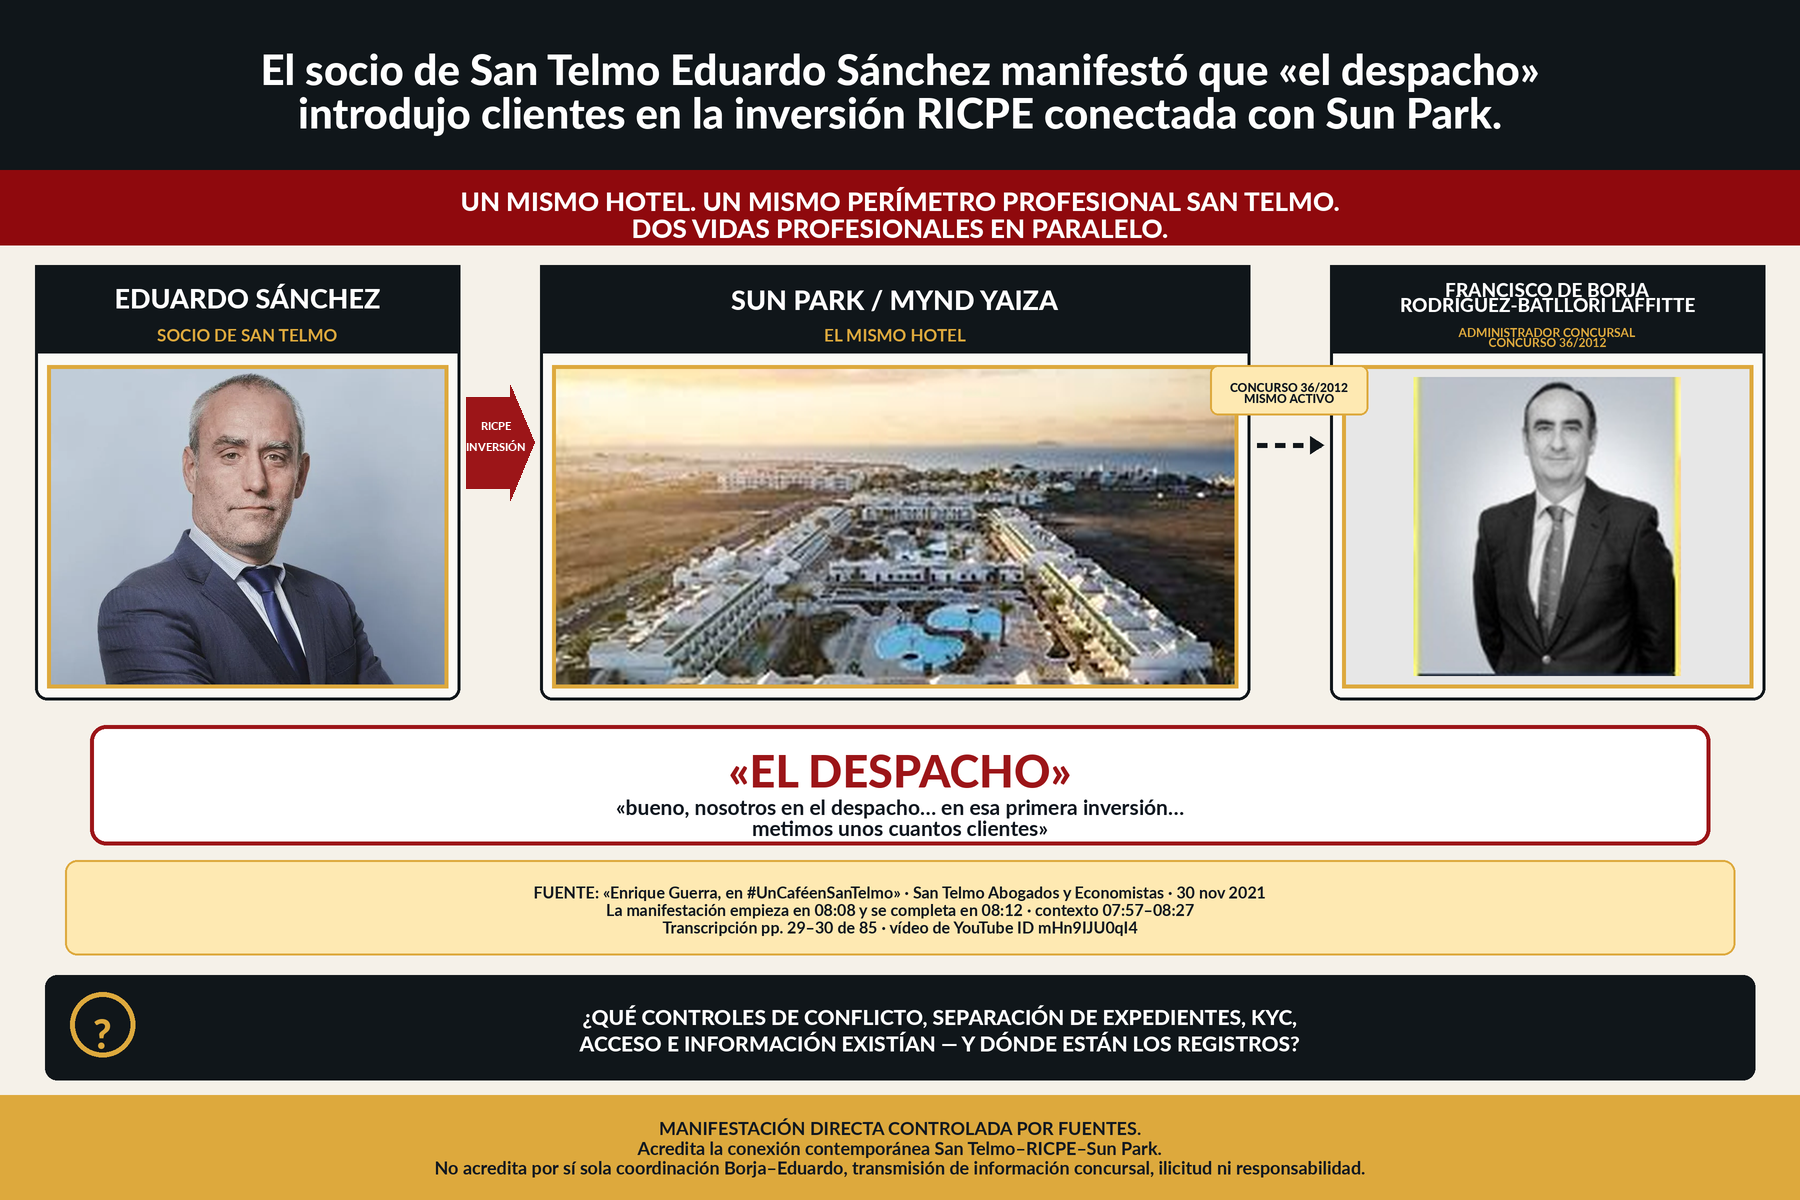
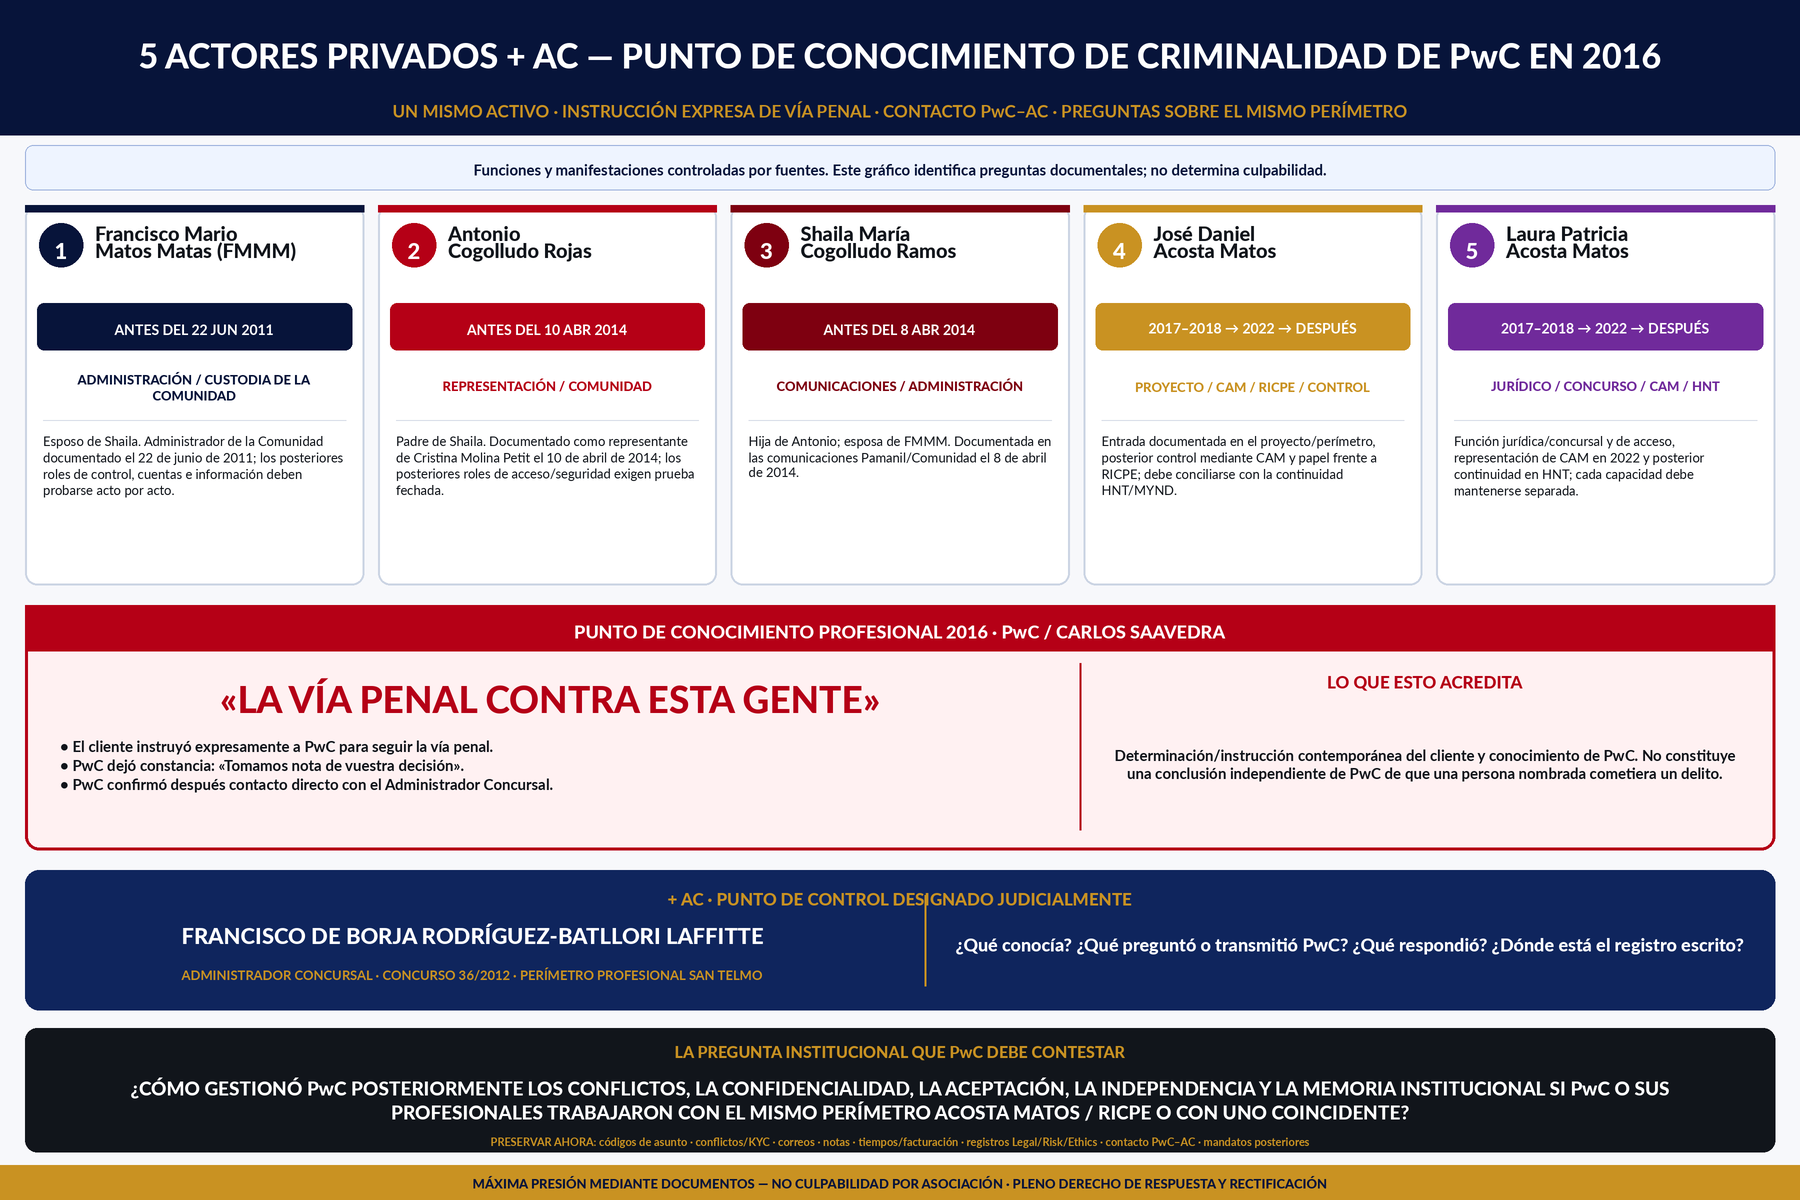
These same 1800×1200 PNGs were attached in recent communications reviewed in the email record to PwC, Grant Thornton, RSM and Fiscalía units. They are embedded here at full source resolution as derivative visual indices: they do not replace the primary evidence and do not by themselves establish coordination, conflict, criminality or liability.
Why this materially sharpens the Uría mandate question
Uría's relevance is not based on guilt by association. RICPE's own history records Juan Francisco Falcón of Uría in the formation/advisory perimeter, and the November 2020 webinar states that Uría Menéndez Madrid handled the lawyers' project-processing/formalisation work generally. The same webinar assigns the described initial legal/tax due diligence to PricewaterhouseCoopers. The correct question is therefore not to pretend Uría performed PwC's diligence, but to establish what Uría's own legal-processing mandate required it to receive, review, reconcile or formalise for Sun Park and its later MYND Yaiza financing continuity.
| Uría record to identify | Why it matters | Boundary |
|---|---|---|
| RICPE engagement letter, matter number, dates, team and scope | Defines whether project processing/formalisation included Sun Park, financing documents, guarantees, project-company authority or investor-facing legal work. | Does not establish a direct CAM retainer. |
| Sun Park / MYND Yaiza project file and instructions | Shows whether Sun Park was merely listed, actively processed, financed, formalised, renamed or paused, and on what assumed ownership/availability basis. | No project-specific Uría work is inferred where the file is absent. |
| PwC / RICPE / CAM inputs supplied to Uría | Tests whether title, encumbrance, litigation, Concurso, Arrecife, unit ownership, common areas, operating rights or project suitability were communicated into Uría's legal-processing lane. | The webinar identifies PwC for initial legal/tax due diligence. |
| Conflict searches and matter-source reconciliation | Relevant because Uría also has an earlier documented PH122/Concurso footprint. Searches should identify whether LPB, Sun Park, Aweswell, CAM, PH122 or related matters appeared. | Historic recurrence does not prove confidential-information transfer or a prohibited conflict. |
| Support for “sociedad titular”, portfolio, ownership and “free of mortgage charges” propositions | Identifies what primary title/registry/Concurso material, if any, sat behind investor-facing asset-availability representations. | No present finding that the representations were false. |
| Legal work around financing, guarantees and RIC materialisation | Tests whether asset availability was a condition or material assumption for the tax-incentive investment proposition and later financing/disbursement architecture. | No conclusion that Uría certified tax eligibility or CNMV approved asset facts. |
Documented notice and challenge history
| Track | What the record supports | What it does not prove |
|---|---|---|
| Intrum / Haya / Meridian | 14 Aug 2024 report; 16 Aug receipt / Ethics Council handling; 6 Sep confirmation that the LPB loan had been packaged in Meridian and later sold; further material in Nov–Dec; Jan 2025 external review said the evidence was insufficiently specific for its whistleblowing route and treated complex NPL sales as outside that channel. | It does not establish the alleged NPL fraud or identical roles/knowledge across all named actors. |
| Banco de España | 26 Nov 2024 whistleblower report to Banking Supervision concerning alleged manipulation of NPL debt and effects on debtor/creditor rights. | Transmission is not acceptance, a licensing determination, supervisory finding or merits decision. |
| CNMV / RICPE | RICPE appears in the CNMV register as SCR no. 295; José Acosta appears as director from November 2019. A later CNMV response records that the July 2021 RICPE certificate and CAM judicial filing were not in the documentation obtained in the earlier supervisory work identified there. | CNMV registration does not validate the truth of Sun Park title/availability representations; CNMV expressly states responsibility for prospectus content lies with the vehicle/manager and CNMV does not verify that content. |
| Fiscalía | 2 Feb 2026 registrations include a filing to the Special Anti-Corruption Prosecutor and an Arrecife follow-up connected to the wider course and EG 19/2026 referral history. | Registration/remittal proves filing state only; it does not prove the offences alleged. |
What evidence could change this interpretation
The thesis must be capable of losing if primary evidence contradicts it. Finite targets capable of confirming, narrowing or refuting material connections:
- Complete originating loan and linked-cover instruments.
- Assignment deed, schedules, price, payment, notices and accessories.
- Concurso ledger and recognition/substitution order.
- Arrecife title and succession/enforcement chain.
- RICPE Sun Park / MYND Yaiza file: title, charges, due diligence and financing.
- Uría engagement, matter, team, sources, conflicts and information-barrier records.
Right of reply: CaixaBank, Uría, RICPE, CAM and any affected party can supply primary material, context or contrary evidence. Correction strengthens the record; silence is not admission.
Submit correction or contrary source →Prepared 14 September 2026 · GitLab is the canonical source authority · right of reply and correction preserved.