One written proposal, two legal mechanisms, and a debt condonation that cannot disappear from the later accounting without explanation.
The recovered 12-page CAM offer combines a proposed dación/payment route for 159 mortgaged LPB apartments with a separate €400,000 direct purchase of 31 fincas. CAM's own economic explanation links the second limb to an approximate €5,186,061.79 debt condonation in the first.
Source boundary. The offer did not itself transfer possession, operation, keys, income, goodwill or third-party title. This reconstruction separates CAM's representation, the Insolvency Administrator's recommendation/implementation, court decisions and LAJ/Registry/notarial acts.
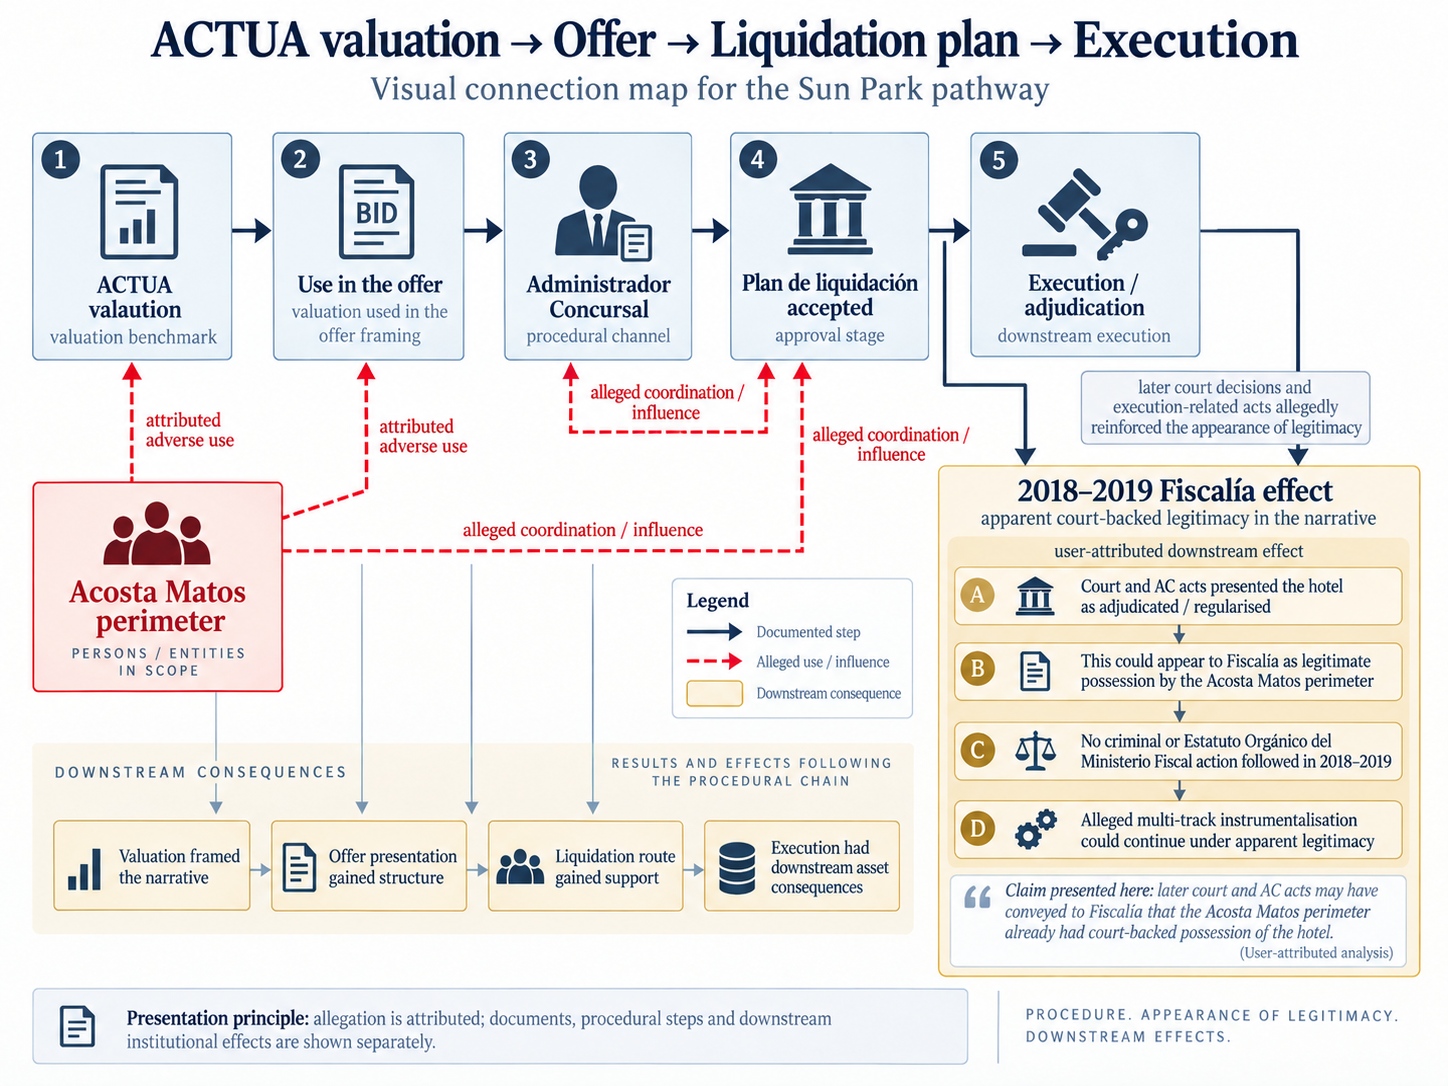
Owner-selected placeholder — provisional, not evidence
This generated diagram is preserved as a provisional illustration. Its claim that no criminal or EOMF action followed is too broad: proceedings and archive decisions existed. The allegation concerns inadequate investigation, protection or supervision. Later 2021–2022 decisions cannot have caused a belief in 2019. Plan approval, physical possession, definitive disposal and conveyance are different events.
Whole-image AVIF display copy, with lossy compression. Open the image for the byte-exact full-resolution original PNG, preserved separately. This generated illustration is not primary evidence or a verified chronology. Its original English composition is retained on both language pages.
SUN PARK · DOCUMENTS → REASONS → DECISIONS → EFFECTS
One hotel. Two mechanisms. One contested chain.
Follow how ACTUA entered CAM’s offer, the insolvency administrator’s recommendation, the court-approved process and its later execution. Each connection identifies what the source establishes—and what remains to be proved.
PROJECT ALLEGATION · Gil Marer / Aweswell allege that misleading valuation premises and selective use of the hotel’s integrated character produced an acquisition advantage and frustrated alternatives. This presentation tests that allegation; it does not declare fraud, corrupt coordination or criminal guilt established.
DOC = documentary statement or recorded act · INFERENCE = stated reasoning or calculation, not a finding · CONTRARY = material counter-record · OPEN = unresolved proof · HIP = attributed hypothesis.
262 / 159 + 31
DOC
The whole hotel is not the insolvency estate.
Start with the connected hotel, then separate the properties the plan proposes to transfer. LPB’s 159 apartments and 31 service/locales/pool titles are not all 262 hotel titles.
262Hotel titles
159LPB apartment branch
31LPB service/pool branch
HOTEL · 262
→
LPB · 159 + 31
→
OTHER OWNERS ≠ LPB ESTATE
FUNCTIONAL DEPENDENCE → operational value, not enlarged ownership
Which exact properties, functions and rights entered each transfer?
The same report. Two different 159-unit allocations.
The arithmetic below reproduces CAM’s and the AC’s figures. It narrows the numerical discrepancy; it does not establish possession of the authors’ worksheets or their reason for selecting a particular allocation.
Calculations in euros. ROUND = round to cents before multiplication. ACTUA’s 57.14% depreciation concerns the construction-cost calculation, not the full value including land.
Dated clarification · 13 September 2026
The two 159-unit figures can now be reproduced by different arithmetic allocations. This narrows earlier wording that their numerical difference was unexplained; the choice, purpose and institutional treatment of those allocations remain open. Earlier versions and contrary evidence are preserved below.
ALLOCATED DIFFERENTLY → trace the input used at each decision
Which accepted calculation included which components, and why?
For the apartments, the AC predicts no surplus after the stated mortgage burden. For the facilities, he moves from dependence on the hotel to the inference that CAM is the only likely buyer. CAM links its claimed apartment-debt forgiveness to the service-property price.
€5,186,061.79CAM’s approximate claimed waiver
€489,361.96ACTUA service reference
€400,000Separate proposed cash price
Branch A · the AC’s economic reasoning
159 apartments
→
6,607,551.87 < 12,251,446.21
→
AC: no surplus → dación
CAM CONNECTS: approximate €5,186,061.79 forgiveness → justification of the €400,000 price. An express offer connection, not proof that forgiveness was already legally effective.
Branch B · the AC’s inference, not a demonstrated necessity
31 service properties
→
Dependent on hotel
→
AC: only buyer → €400,000
SUPPLIED → INFERRED → RECOMMENDED; the two price arguments stay connected
Does dependence on the hotel justify ‘CAM is the only buyer’, or does it call for integrated competition?
The objections and safeguards must travel with the approval.
LPB/Aweswell’s objections and a higher competing valuation were before the court. The order approved a disposal process with qualifications, publicity and an opportunity for improved bids. It was not a blanket authorization for whole-hotel possession.
16 APR 2018Qualified plan approval
10 DAYSBetter-offer opportunity
26 JUN 2018Apartment realisation stay
16 APR · approval
→
17 APR · later ACTUA response
The 17 April filing could not cause the 16 April order. March receipts place the GESVALT disagreement before the order, without proving personal reading or intent. 18 January (judicially recorded date) and 9 February (recovered name/version) are not conflated.
OBJECTED → CONDITIONALLY APPROVED → EXECUTION MUST FOLLOW THE TERMS
What was actually notified, compared, authorized and then done?
The service-property branch was executed through Protocol 2150 in November 2018. The AC later reported the €400,000 receipt and applications. In October 2019 the court refused convalidation, identifying departure from the unitary process and its own earlier error.
28 NOV 2018Separate service-property deed
€400,000AC-reported receipt and applications
24 OCT 2019Convalidation refused
Apartments · realisation stayed
26 JUN 2018
→
159 apartments
Facilities · branch executed separately
28 NOV 2018 · P2150
→
€400,000 · AC reports receipt
24 OCT 2019 · Court refuses convalidation. OPEN: contractual, Registry, possession and cash-restoration acts.
SEPARATED → JUDICIALLY REJECTED; practical restoration is a separate evidential step
What restored title, possession, operation and the money before the same facilities were offered again?
The deed continues the plan—not a cash-payment story.
The 2021 decision refers back to the 2018 plan. Protocol 457 in 2022 invokes the judicial route and states €13,168,082.02 as debt consideration. The third-party bidder’s failure to meet the bond/attendance requirements and the court’s contrary findings remain visible.
18 MAY 2021Definitive proposal approval
21 FEB 2022Protocol 457
€13,168,082.02Stated debt consideration—not cash
2018 · terms
→
2021 · definitive approval
→
2022 · P457
Proposed forgiveness, any completion condition, a bidder threshold and the debt ultimately discharged are different categories. Double recovery or disappearing cash is not presumed. Locate the legal act and accounts connecting them.
REAPPROVED → CONVEYED; reconcile debt, waiver, €400,000 and Registry effects
Which act and account connect the 2018 terms to the final debt extinguished and actual property transfers?
The proposed Montelanza/Molina → CAM connection requires unit, condition, access, information-provider and later-use evidence for each actor. ACTUA’s mixed 13-photo record and three clear apartment interiors do not identify Blocks 4–5 or their owners. 44, 60 and 61 are different source denominators.
No retrospective authority
Physical control in June 2018, a disposal approval, a 2019 prosecutorial statement and a 2022 conveyance are different events. A later decision cannot cause an earlier belief or retrospectively authorize every earlier act. The separate Fiscalía analysis must identify its actual received documents and stated reasons.
What would close the remaining links?
The calculation workbook and accepted price formula; original transfer and payment records; exact post-2019 restitution/Registry acts; bidder disclosures; and the debt, interest, waiver and cash reconciliation. Those are existing case-evidence obligations, not invented proof.
Inspect the source and the boundary
ACTUA · valuation and functional dependence · 2018-01-15 · DOC
ACTUA-2018-PRIMARY
Original report, service-property explanation and individual valuation schedule; printed pp. 2, 45–46.
The individual schedule gives €41,556.93 per apartment. Fincas 8653/8654 carry asterisks because their value is included in the apartments, not a zero independent value. The photographic/access and purpose limitations remain material.
CAM’s 12-page offer, pp. 5 and 7–10; inspect the conditions with the figures.
Construcciones Acosta Matos, S.A. proposed a €7,065,384.42 apartment limb and approximate €5,186,061.79 forgiveness against stated debt. It invoked that forgiveness when justifying €400,000 for the 31-property limb. Legal-form and finca-list discrepancies are not silently corrected.
Plan §5.5, printed pp. 9–12 (physical pp. 11–14 of the reviewed 16-page manifestation).
lo que hace suponer a la AC que el único comprador potencial de las mismas es la entidad Construcciones Acosta Matos, S.A.
The AC says CAM supplied ACTUA for a purchase/dación proposal, attaching the valuation as Annex I and offer as Annex II. He compares €6,607,551.87 to €12,251,446.21, predicts no auction surplus, and infers CAM is the only likely purchaser of the service properties. The plan states that the whole-complex value includes property outside LPB’s estate.
Approval order: objections, qualifications and operative disposal provisions.
The order records the lower-valuation objection and a higher competing valuation, and approves the disposal with publicity and an opportunity for improved bids. It records presentation of the plan on 18 January; the recovered filename/earlier page uses 9 February, which remains a version/date distinction, not a silent correction.
Operative stay affecting the specified apartment realisation.
The June stay is a real contrary/protective act. It follows the alleged 7 June material-control shift and must not be drawn as an already-existing order breached on that day.
AC quarterly report: 28 November deed, €400,000 cheque and applications.
The AC reported receipt and collection of the €400,000 cheque and payment of specified AC fees, with other creditor-payment steps. This is an AC-authored account, not independent bank reconciliation. Do not label the sum ‘never paid’.
Reasoning on unitary disposal, third-party competition, prior judicial error and refusal to convalidate Protocol 2150.
The order states that the separate sale departed from the approved unitary process, acknowledges the court’s earlier error and explains why the facilities matter to improved integrated bids. It refuses convalidation and sets aside the December 2018 direction. Complete contractual, Registry, cash and possession reversal is not proved by that refusal alone.
Definitive proposal approval; competition, publicity and bidder/bond findings.
The later order approves CAM’s proposal by reference to the 2018 plan. The competing bidder’s bond/nonattendance and the court’s rejection of objections remain material adverse evidence. They are not omitted merely because the project challenges the process.
Protocol 457, operative dación provisions, pp. 28–29 of the controlled 76-page copy.
The deed invokes the judicial approvals and execution of the liquidation plan. Its €13,168,082.02 is stated debt consideration, not a cash receipt of that amount. Mortgage-cancellation requests and the five-day court-reporting provision require their own execution evidence.
These cards are source-qualified summaries and short extracts, not facsimiles or certified court copies. Existing documentary pages remain available; a missing public original is not silently replaced by a reconstruction. JSON
The complete earlier record continues below
Figures that must remain separate
€12.251m
CAM debt premise
At 20-Oct-2017 before later interest. Not automatically the final allowed insolvency credit, set-off amount or price.
€9.776m
ACTÚA whole complex
A wider physical/economic perimeter than the LPB real-estate estate.
€7.065m
first mechanism · 159
€7,065,384.42 attributed to the dación/payment limb.
€5.186m
stated condonation
≈€5,186,061.79, expressly used by CAM in the economics of the second limb.
€489,361.96
ACTÚA · 31 fincas
Appraisal reference for locales/pools-solaria and operating-support assets.
€400,000
second mechanism · direct sale
Separate cash price whose economic justification CAM linked to the first-limb condonation.
No-double-count control. If condonation was counted as value/sacrifice supporting the 2018 package and the €400,000 price, a later account cannot simply treat the same amount as debt that remained fully live and was later satisfied. If a later act displaced it, identify that legal bridge.
IBI, waste charges and “other expenses”: municipal liability is not the same as the final economic burden
1 · Municipality Who was legally billed for the tax/rate and for which property/period?
2 · Exploitation contract Who was contractually meant to bear IBI, waste, Community, maintenance and utility costs?
3 · Actual payment Who actually paid, from which account, and how was it booked?
Current evidential baseline. Jonathan Simó's recovered work attributes a substantial operating-cost burden to hotel exploitation and the 2008–2015 version includes approximately €70,487.20 of waste/tax items within expenditure classified as borne by the exploitation. The 2016 recorded meeting also shows that owner contracts differed and that in some arrangements the operator bore Community charges and, depending on the contract, IBI.
14–15 Feb 2018 · contemporaneous separation put to Yaiza's collection office. Patricia expressly requested two ledgers: IBI for LPB only and waste charges for the operator/exploitation entity, Cdad. de Explotación Sun Park. She said the 2017 waste charge should be moved from LPB to the operator account, “where it belongs”, and the previous day had written that the waste charge “belongs to the operator of the complex”. This documents the operating side's contemporaneous allocation position; it does not by itself prove that Yaiza legally completed the requested reassignment.
22 Feb 2018 · what the located municipal response actually proves. Yaiza sent two grouped payment letters for €263,733.38 and €48,941.22. The reviewed copy is headed LUCHY PLAYA BLANCA SL and the inspected entries are IBIU. The separate waste/CEXP ledger requested has not been located in that copy. Therefore: LPB's municipal collection identity for the IBI is documented; formal municipal reassignment of waste to CEXP remains open pending the corresponding ledger/payment letter.
Offer-value consequence. CAM's promise to assume IBI, waste, Community or other expenses cannot automatically be counted as extra estate consideration. Each item first needs classification as: (i) a formal municipal LPB liability; (ii) a cost contractually passed to exploitation; (iii) a CEXP/operator liability; (iv) an amount already paid or funded by exploitation; (v) a contingent/disputed liability; or (vi) a genuinely new closing cost borne by CAM. Only the incremental burden that ultimately belonged to LPB/the estate, remained unpaid and was actually discharged by CAM can be counted as added value.
Legal control: IBI generally addresses the holder of the taxable property right, while Spanish local-finance law preserves private-law pass-through. For local service charges benefiting occupiers, the owner may be a substitute taxpayer with possible pass-through to the beneficiary. The applicable contract and municipal ordinance still matter period by period. Evidence rule: “statutory taxpayer”, “economic bearer”, “actual payer” and “CAM consideration” are four different fields.
“Free of charges” does not mean “free of OB REM” or “free of economic outgoings”
17 Jan 2018 · Patricia
Patricia contemporaneously described the offer as condonation + dación + payment for locales “without charges”. That remains her then-current description; it is not converted into Registry proof that the properties were free of every encumbrance.
Dec 2018 · Cuatrecasas re-check
The team specifically rechecked whether the registered OB REM obligation appeared on title notes for fincas treated as “free of charges”. Rosa Gual then reported that four fincas were in fact burdened by the OB REM obligation and the court pleading would be corrected.
Three mandatory fields:FREE_OF_MORTGAGE · OB_REM_YES/NO · OTHER_TAX/COMMUNITY/CONTRACTUAL_BURDENS. One source's “free of charges” label does not populate the other two.
Chart 1 · one offer, two offers, or one composite offer?
15 Jan 2018 single CAM document
→
Limb A 159 apartments dación/payment ≈€7.065m
+
Limb B 31 fincas direct sale €400,000
Controlled source: CAM refers to the “CONDONACIÓN de DEUDA efectuada en la primer oferta”, approximately €5,186,061.79, as part of its justification for the second limb. The IA Plan also describes a “unitary acquisition offer” for the debtor's productive unit/real-estate assets while exposing components separately.
Possible benign reading
One commercial package used two legal techniques because the apartments were mortgaged while the other assets were not. The limbs may have been legally severable while economically linked.
Reconciliation problem
If unity supported the discount, condonation and competitive comparison, what legal/economic treatment applied when one limb was later executed separately?
Project position. The Project investigates whether unity/severability was used asymmetrically. The more serious hypothesis—deliberate ambiguity used to obtain patrimonial/procedural effects—requires actor-specific native proof of knowledge, intent, use and causation. It is not an adjudicated finding.
Chart 2 · five coherent audit outcomes for the condonation
A · binding remissionIf perfected as part of the approved composite bargain, the remitted amount cannot revive without a valid later act.
B · conditional remissionIf dependent on linked completion, suspension/non-completion may prevent crystallisation; the €400,000 price then needs a new explanation.
C · arithmetic onlyIf not a juridical remission, it cannot simultaneously be presented as an independent €5.186m sacrifice enhancing CAM's offer.
D · superseded 2021–22Identify the exact later order/novation/offer and reconcile debt, €400,000, bidder threshold and closing accounting.
E · variable amountIf linked to valid enforceable debt, reconstruct the instruments, grace-period change, interest, security, classification and liquidation euro by euro.
Gate. A sixth outcome may be added only with the primary source and legal bridge that creates it.
Preferential acquisition / retracto: alleged sabotage, but route by route
PP/DP 1041 · PH122→CAM credit
On 19-Dec-2017 a court admitted preliminary disclosure seeking the assignment deed, price, payment and costs. It did not decide that an Article 1535 retracto had been won. On 25-Jan-2018 the IA ended Cristo's specific formal LPB mandate; on 5-Mar the file records LPB's withdrawal and closure.
Project hypothesis: a live judicial information route capable of testing Article 1535 and other debt/negotiation options was neutralised. The exact withdrawal instruction and estate-interest analysis remain open.
25 May 2018 · funded-exit preferential option
Separately, Patricia/Aweswell prepared a six-month preferential acquisition option for Lagune Hospitalidad/Batipart, conditional on financing sufficient to repay LPB debt. This belongs to the contractual funded-exit lane, not the credit retracto.
There is no single generic “tanteo”. The repository separates Article 1535 credit rights, unit-transfer rights analysis, co-owner retracto and contractual/tourism/exploitation rights. The former Canary statutory preference investigated by counsel was not an operative 2018 basis.
Locales / pools · OB REM · effect on the original package
Event
Control
Open question
26 Jun 2018
Court stays the mortgage-finca realisation route.
Which part of the composite economics remained executable?
28 Nov 2018
IA executes OB REM delinking/cancellation and €400,000 direct sale of the 31-finca limb.
How did the condonation/price rationale survive separate execution?
Jan–Mar 2019
Registry obstacle + IA convalidation request.
What authorising title was missing and what material effects existed meanwhile?
24 Oct 2019
Court refuses convalidation.
Was title/use/possession restored, was OB REM restored, and how was €400,000 accounted? Non-convalidation alone does not prove a completed material unwind.
2021–22
Competition/reapproval + apartment dación.
What later act replaced, cured or reincorporated the 2018 limb?
Do not conflate this with the ONA lease. A signed hotel-industry lease dated 6-Jun-2018 is verified. This pass did not locate a primary termination/cancellation instrument. Frustration or destruction of that funded-exit route is a causation question, not a fact silently attributed to the locales deed.
Chart 3 · from secured creditor to material-control creditor
CAM mortgage-credit holder 20 Oct 2017
→
7 Jun 2018 source-supported alleged/documented material access/security-control threshold
→
CAM's own post-acquisition conduct separate liability/accounting perimeter
Spanish functional equivalent
There is no autonomous Spanish status called lender in possession. The controlled comparator is secured/mortgage creditor in de facto material possession or control. Examine administrador de hecho separately only if sustained genuine management/instruction power is proved.
A mortgage is not a self-help licence
Spanish mortgage law subjects collateral to the debt, but where collateral value is impaired Article 117 Ley Hipotecaria directs the creditor to judicial protective measures, potentially judicial administration. That is not a mortgage-derived right to seize the whole hotel, alter access, carry out works or destroy operations by self-help.
Correct consequence. Even if unlawful CAM-caused physical or business damage were proved, the mortgage debt does not automatically vanish. Separate estate/debtor claims may arise for restoration, diminution, fruits/rents, lost profit, restitution and other legally proved loss. Insolvency set-off must follow the applicable insolvency rules; it is not private self-help.
Private economics, condonation and two mechanisms; no present title/control.
17 Jan
Patricia contemporaneous note
Describes condonation+dación+locales “without charges”, a full hotel and contemplated disclosure/tanteo; evidence of contemporaneous understanding/notice, not title.
25 Jan → 5 Mar
Cristo mandate / DP1041
IA ends specific formal mandate; file later records LPB withdrawal. Exact internal instruction remains open.
9 Feb
Controlled IA Plan
IA recommends CAM route and uses ACTÚA.
14–22 Feb
Yaiza · IBI / waste
Patricia asks that LPB IBI and operator/CEXP waste be separated; the recovered payment letters remain headed LPB and contain IBI. Formal waste reassignment remains open, while the contemporaneous operating allocation position is documented.
16 Apr
Plan approval + separate interest ruling
Judicial gates; not whole-hotel possession/operation authority.
23 Apr
Cuatrecasas description
Describes CAM as assuming IBI, contingent Community and other costs; those items require taxpayer/contract/payment reconciliation before being counted as added consideration.
25 May / 6 Jun
Preferential option + hotel-industry lease
Separate funded-exit components; not Article 1535.
7 Jun
Material access/control change
Alleged causal threshold for operation/exit harm; not legal possession of the whole hotel by itself.
20 Jun
Patricia unjust-enrichment theory
Contemporaneously attributes assumed alleged Community liabilities to Matos within the acquisition theory; party allegation, not validation of that debt.
26 Jun
Realisation stay
Real protective act, adverse to a simplistic one-direction bias narrative.
28 Nov 2018 → 24 Oct 2019
Protocol 2150 → non-convalidation
IA executes 31-finca limb; court later refuses convalidation; material/accounting aftermath remains to be reconciled.
2021
Competition / Ottawa / CAM approval
A later competitive control point existed; equality of economic/legal footing still requires full reconstruction.
21 Feb 2022
Protocol 457
LPB apartment dación with stated ≈€13.168m debt consideration; requires bridge to condonation, interest, actually paid IBI/Community items and final accounts.